Beyond the Unicorn: Why Britain’s Next Founders Are Building Businesses That Last
Ask a founder in 2026 what success looks like and you may get a different answer than you would have done a decade ago. The old script was simple: raise money, grow fast, hire hard, list or sell. The new script is messier, slower and, frankly, more interesting. A growing number of British founders are building what some call zebra businesses: profitable, resilient, purpose-driven companies that measure success in customers served, people paid fairly and problems solved, not just valuation multiples.
That is not a rejection of ambition. It is a different kind of ambition. And it deserves more attention from investors, policymakers and anyone who claims to care about the UK's long-term productive capacity.
The unicorn hangover
The unicorn was a useful shorthand for a private company worth more than a billion dollars. It was also a handy way to avoid asking harder questions. Was the business profitable? Did it treat its staff well? Did it make something useful? Did it depend on cheap capital and endless rounds? For a while, in the low-rate years before 2022, those questions felt optional. Then the money got more expensive, the exits dried up and a lot of very fast companies discovered that speed is not the same as strength.
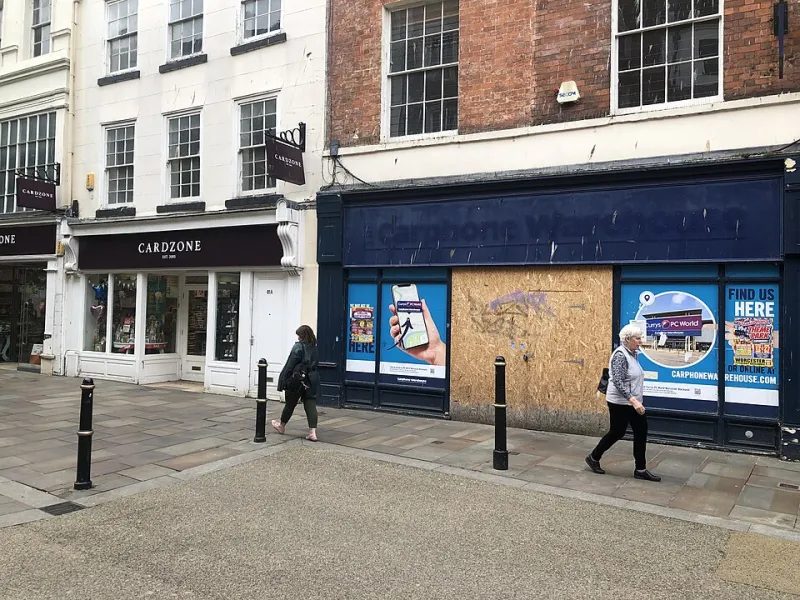
Britain has plenty of scars from that period. Founders who scaled too soon. Teams hired for growth that never arrived. Town centres left with another empty unit. None of this means venture capital is bad. It means the UK's startup ecosystem has been too narrow in how it defines success. The Big Ideas view is simple: a country needs high-growth, venture-backed firms. It also needs thousands of businesses that can survive a shock, keep people in work and stay rooted in their places.
What a zebra looks like in practice
Zebra firms are not a formal legal structure. They are a pattern. You can see it in employee-owned businesses, B Corps, co-operatives, social enterprises and ordinary family firms that decide not to sell out to the highest bidder. Riverford, the organic veg box company, is employee-owned. Cafédirect has built a business around smallholder farmers. A growing number of UK design studios, retrofit firms and food producers are certifying as B Corps or adopting pay ratios and ownership models that share the upside more widely.
The pattern shows up in smaller ways too. A Bristol food business that sells through independent shops rather than chasing supermarket volume. A Manchester software co-op that caps its pay ratio and reinvests surplus in training. A Yorkshire retrofit company that trains apprentices and pays them properly. These firms are not trying to be everything to everyone. They are trying to be useful, profitable and around in ten years' time.
That matters because the UK's economic challenge is not just about creating more startups. It is about creating more companies that last. The average age of a UK business matters for productivity, innovation and local wealth. A town with a cluster of stable, locally owned firms has more resilience than a town with one distant investor-owned employer.
Finance beyond the term sheet
If zebra businesses are so sensible, why are they still hard to finance? Partly because the UK's investment plumbing is built for a particular kind of company. Venture capital wants a small number of enormous outcomes. Banks want collateral. Many founders want neither a 10-year plan to sell nor a personal guarantee on their house.
There are practical alternatives. Revenue-based finance lets a company repay investors from future sales without giving away ownership. Community shares can fund a local food hub, a renewable energy project or a community-owned pub. Blended finance, where public or philanthropic money takes the first loss, can make early-stage impact investing more attractive. Employee ownership trusts offer a succession route that keeps a business rooted.
Policy could help without inventing a new quango. The UK's SEIS and EIS schemes are genuinely useful, but they could be tuned to reward patient holding periods rather than quick exits. The British Business Bank and regional funds could reserve a slice of capital for place-based investors who back zebra-style firms. Local authorities and anchor institutions could publish procurement pipelines so smaller, responsible suppliers can bid. Business support should include advice on co-operative conversion, employee ownership and community shares, not just accelerator programmes for app startups.
Investors also need better scorecards. Gross margin, staff retention, customer concentration, local supplier spend and employee ownership are not soft metrics. They are signals of durability. A fund that only measures total addressable market will keep missing companies that are quietly building something valuable.
The ambition is still big
None of this is about telling founders to think small. A zebra firm can scale. It can export. It can innovate. It can become an anchor employer in its region. The difference is that it tries to grow without hollowing out the things that made it work in the first place.
Britain's next great company might never appear on a unicorn list. It might be an employee-owned engineering firm in the Midlands, a community-backed retrofit business in Wales or a software co-op selling into Europe from a converted high street unit. It might grow steadily, pay its taxes, train its people and still be here in 2046.
That sounds like a better idea of success. And it is one the UK should be actively building for.